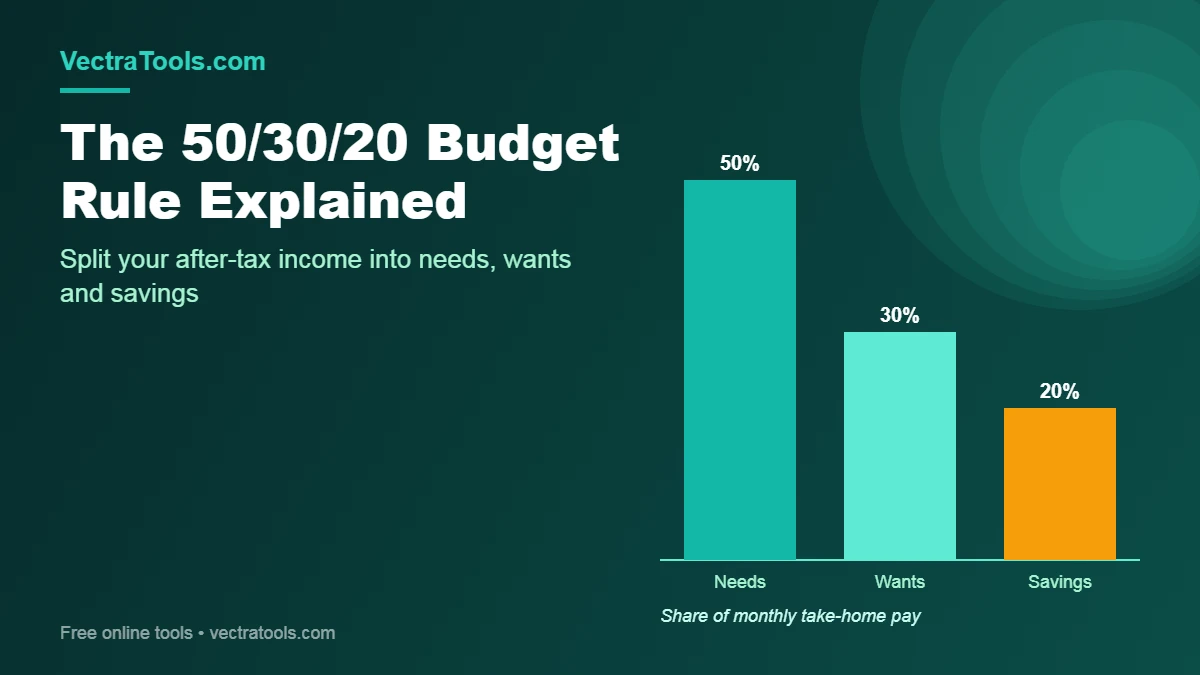
Quick answer: The 50/30/20 budget rule splits your monthly after-tax income into three buckets: 50% for needs (rent, food, bills), 30% for wants (dining out, hobbies, subscriptions) and 20% for savings and extra debt payments. On a $4,000 take-home salary that means $2,000 for needs, $1,200 for wants and $800 for savings. Get your exact split in seconds with our free 50/30/20 Budget Calculator.
Most budgets fail because they are too detailed. Tracking 25 categories feels great for a week, then life happens. The 50/30/20 budget rule works because it is simple enough to remember and flexible enough to survive real life. In this guide you will see how the 50/30/20 budget rule works, 3 worked examples, what goes in each bucket and how to adjust it when your costs are high.
Where Did the 50/30/20 Budget Rule Come From?
The rule was popularised by Elizabeth Warren, a former Harvard bankruptcy law professor and now a U.S. senator, and her daughter Amelia Warren Tyagi in their 2005 book All Your Worth: The Ultimate Lifetime Money Plan. Their idea was to replace line-by-line tracking with a balanced framework anyone could follow. Financial outlets such as Fox Business still recommend it as a starting point for beginners.
How the 50/30/20 Budget Rule Works
50% – Needs
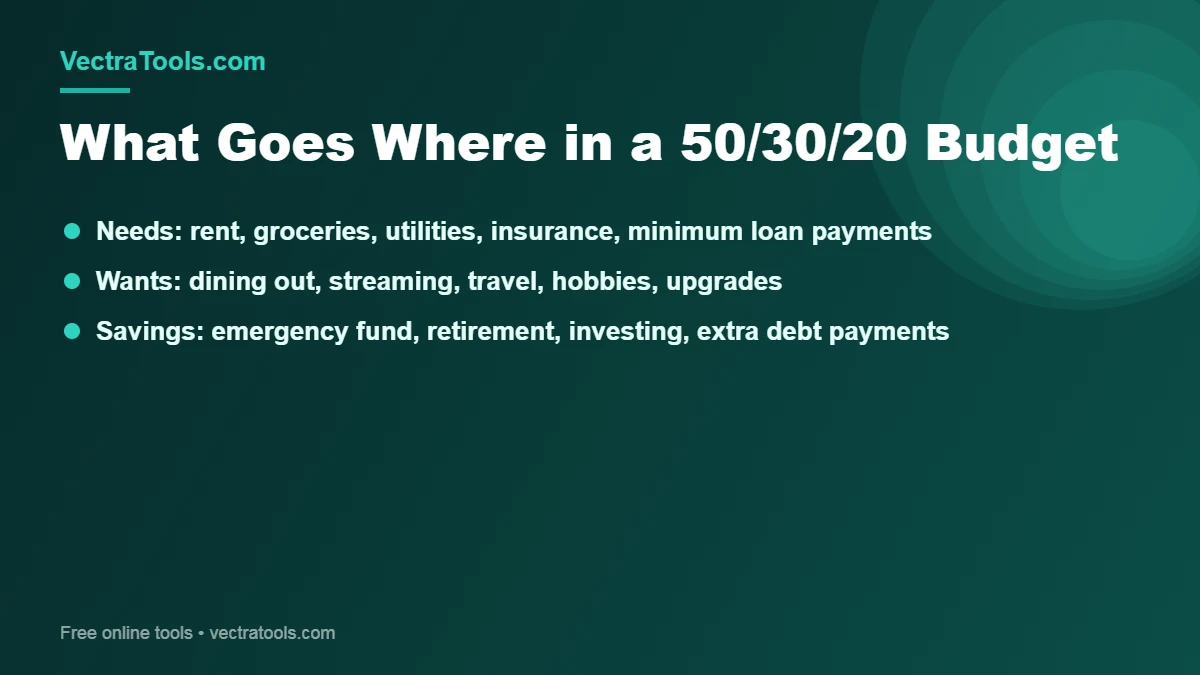
Needs are expenses you must pay to live and work: rent or mortgage, utilities, groceries, basic transport, insurance, childcare and minimum loan payments. If you skipped them, something serious would happen.
30% – Wants
Wants make life enjoyable but are optional: restaurants, takeaway, streaming services, shopping, travel, gym upgrades and the newest phone. This bucket is what makes the plan sustainable – you are allowed to enjoy your money.
20% – Savings and debt repayment
This bucket builds your future: an emergency fund, retirement contributions, investments and any debt payments above the minimum. Money here benefits from compounding – see our guide on compound interest vs simple interest to understand why starting early matters.
3 Examples of the 50/30/20 Budget Rule
Always use take-home pay (after tax), not gross salary. If you only know your gross pay, estimate your net income with our Income Tax Calculator or Salary Calculator first.
| Monthly take-home | Needs (50%) | Wants (30%) | Savings (20%) |
|---|---|---|---|
| $2,500 | $1,250 | $750 | $500 |
| $4,000 | $2,000 | $1,200 | $800 |
| $6,500 | $3,250 | $1,950 | $1,300 |
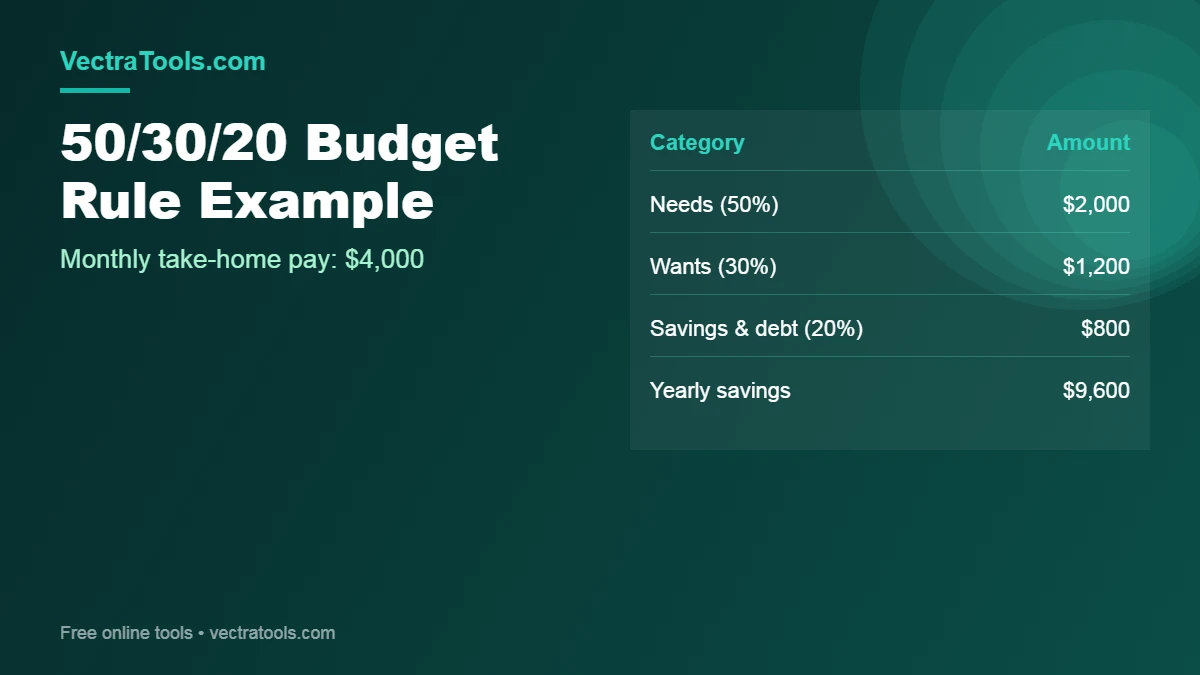
At $4,000 a month, the 20% savings bucket adds up to $9,600 a year. Paid hourly? Convert your rate to a yearly and monthly figure with our Hourly to Salary Converter before you split it.
How to Set Up a 50/30/20 Budget in 5 Steps
- Find your monthly take-home pay. Use your payslip or bank deposits. Include side income only if it is regular.
- List last month's spending. Export bank and card statements and tag every expense as need, want or savings.
- Compare with the 50/30/20 targets. Plug your income into the 50/30/20 calculator and see how far off you are in each bucket.
- Automate the 20%. Set an automatic transfer to savings on payday so saving happens before spending.
- Track monthly. Use our free Budget Planner to log categories and review once a month.
When the 50/30/20 Budget Rule Needs Adjusting
The 50/30/20 budget rule is a guideline, not a law. In high-cost cities, needs can easily take 60% or more of take-home pay. Common variations:
- 60/20/20: for high rent areas – trim wants, protect savings.
- 70/20/10: for tight budgets or early careers – keep saving something, even 10%.
- 50/20/30: for aggressive savers or anyone paying down high-interest debt.
If loan payments are pushing your needs above 50%, check the real cost of each loan with our EMI Calculator and consider whether refinancing could lower the monthly amount.
Pros and Cons of the 50/30/20 Budget Rule
| Pros | Cons |
|---|---|
| Easy to remember and start | 50% for needs is unrealistic in some cities |
| Guilt-free spending on wants | Not detailed enough for complex finances |
| Builds a savings habit automatically | Irregular incomes need a monthly average |
| Works for any income level | Need vs want can be a grey area |
Frequently Asked Questions
What is the 50/30/20 budget rule?
It is a budgeting method that puts 50% of after-tax income toward needs, 30% toward wants and 20% toward savings and extra debt payments.
Is the 50/30/20 rule based on gross or net income?
Net income. Use your take-home pay after taxes and mandatory deductions.
Do debt payments count as needs or savings?
Minimum payments are needs. Anything you pay above the minimum goes in the 20% savings and debt bucket.
What if my needs are more than 50%?
Reduce wants first, then look for cheaper housing, transport or insurance. A 60/20/20 split is a common workable alternative.
Is the 50/30/20 budget rule good for beginners?
Yes. It is one of the simplest ways to start budgeting because it uses only three categories.
This article is for general education only and is not financial advice. Adjust any budget to your own situation.