

Fixed Deposit (FD) Penalty Calculator – Premature Withdrawal in 3 Easy Steps
FD Penalty Calculator
Use this fixed deposit (FD) penalty calculator to get your exact payout, revised interest rate, and penalty amount if you break your Fixed Deposit early.
Use this free Fixed Deposit (FD) Penalty Calculator to see exactly what you will receive if you break a fixed deposit before it matures. Enter the principal, original interest rate, original tenure, the month you plan to withdraw and your bank’s penalty rate, and the tool shows the payout, effective interest rate, penalty and the interest you give up.
Quick answer
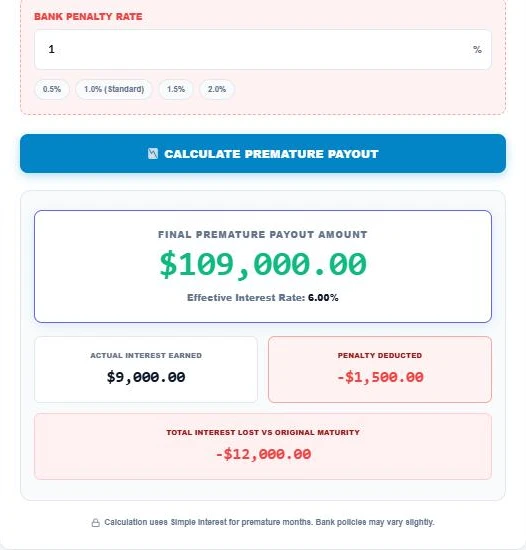
When you close an FD early, banks usually pay interest at the applicable rate minus a penalty, often 0.5% to 1%, for the time the money was actually deposited. For a 100,000 deposit at 7% for 36 months broken after 18 months with a 1% penalty, the effective rate falls to 6%. You earn 9,000 in interest, lose 1,500 to the penalty, and receive 109,000, which is 12,000 less interest than holding to maturity.
Table of Contents
Fixed deposits are popular because the return is guaranteed, but life does not always wait for the maturity date. A medical bill, a house deposit or a better investment can make you want the money now.
This Fixed Deposit (FD) penalty calculator shows the real cost of breaking the deposit before you visit the bank, so you can compare it with other options such as a loan against the FD.
What Is a Premature FD Withdrawal Penalty?
A premature withdrawal penalty is the reduction in interest a bank applies when you close a fixed deposit before its term ends. Instead of paying the rate you were promised, the bank pays a lower rate for the period you held the deposit. The penalty compensates the bank for planning around your money for longer.
How the FD Penalty Is Calculated
- Effective rate = original interest rate − penalty rate
- Interest earned = principal × effective rate × (months held ÷ 12)
- Penalty amount = principal × penalty rate × (months held ÷ 12)
- Payout = principal + interest earned
- Interest lost = interest at maturity − interest earned
The Fixed Deposit (FD) penalty calculator uses simple interest for clarity. Many banks compound FD interest quarterly and apply the card rate for the shorter period actually held, so your bank’s figure may differ slightly.
How to Use the Fixed Deposit (FD) Penalty Calculator
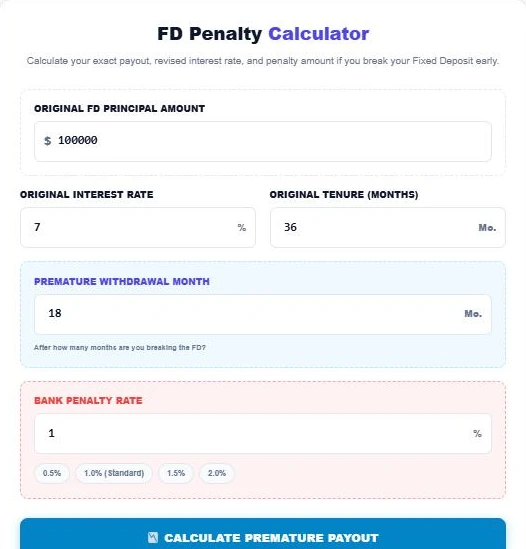
Step 1: Enter Your FD Details
Type the original principal, the interest rate on your FD receipt and the original tenure in months. Then enter the month in which you plan to withdraw and your bank’s penalty rate, or tap a quick button for 0.5%, 1%, 1.5% or 2%.
Step 2: See Your Premature Payout
Press Calculate Premature Payout. In this example the effective rate drops from 7% to 6%. You receive 109,000 in total: 9,000 of interest after a 1,500 penalty. Compared with the 21,000 of interest you would have earned by holding for 36 months, you give up 12,000.
Step 3: Compare a Later Withdrawal or Lower Penalty
Change the withdrawal month or penalty to compare options. Breaking the same FD at month 30 with a 0.5% penalty gives a 6.5% effective rate, 16,250 of interest and a payout of 116,250, so you lose only 4,750 versus maturity.

FD Penalty Examples
| Principal | Rate | Held for | Penalty | Effective rate | Interest earned |
|---|---|---|---|---|---|
| 100,000 | 7% | 18 months | 1% | 6% | 9,000 |
| 100,000 | 7% | 30 months | 0.5% | 6.5% | 16,250 |
| 50,000 | 6.5% | 12 months | 1% | 5.5% | 2,750 |
| 200,000 | 7.5% | 24 months | 1% | 6.5% | 26,000 |
Alternatives to Breaking Your FD
- Loan or overdraft against the FD: many banks lend up to about 90% of the deposit at a rate slightly above the FD rate, and your deposit keeps earning.
- Partial withdrawal: some banks allow you to withdraw part of the deposit while the rest continues.
- Split future deposits: open several smaller FDs with different maturity dates (an FD ladder) so you only break what you need.
- Keep an emergency fund in a savings account so you rarely need to touch fixed deposits.
Tips to Reduce FD Penalties
- Read the premature withdrawal clause before opening an FD.
- Ask whether the penalty is waived after a certain period or for senior citizens.
- Compare the penalty cost with the interest on a short personal loan.
- Choose tenures that match when you expect to need the money.
Planning long-term savings instead? Try the PPF Maturity Calculator or see how inflation affects your returns with the Inflation Purchasing Power Calculator.
Frequently Asked Questions
What is the penalty for breaking an FD early?
Most banks charge 0.5% to 1% less than the applicable interest rate for the period the money was deposited. Some waive the penalty for senior citizens or after a minimum period.
How is premature FD interest calculated?
Interest is worked out at the reduced rate, usually the applicable rate minus the penalty, for the months the deposit was actually held.
Do I lose my principal if I break an FD?
No. You get your full principal back. Only the interest is reduced.
Is it better to break an FD or take a loan against it?
For short-term needs, a loan against the FD is often cheaper because your deposit keeps earning while you repay.
Why is my bank’s figure different from the calculator?
Banks may use the card rate for the shorter tenure and quarterly compounding. The calculator uses simple interest on your original rate minus the penalty.
Is my data stored?
No. The Fixed Deposit (FD) penalty calculator runs entirely in your browser.